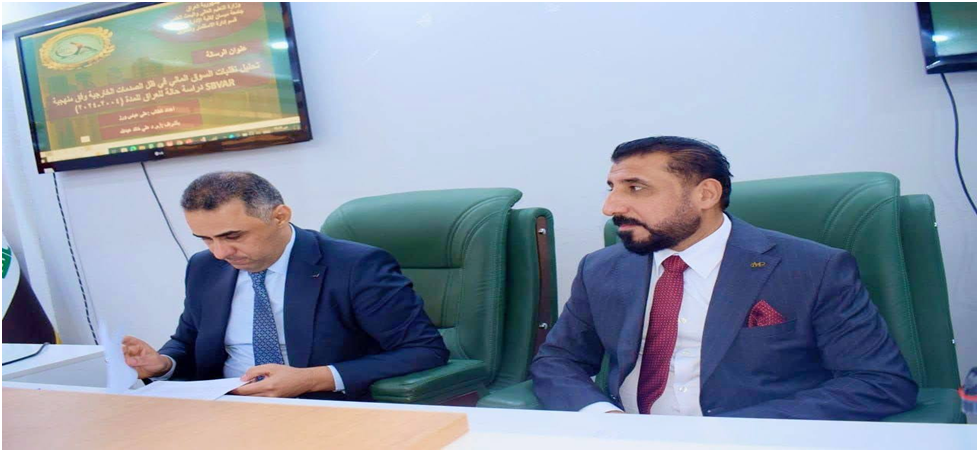
The Department of Business Administration/Investment and Finance Management at the Faculty of Administration and Economics, University of Misan, organized a scientific seminar to discuss a master’s thesis proposal entitled: “Analysis of Financial Market Fluctuations under External Shocks According to the MethodologySBVAR: A Case Study of Iraq (2004–2024), by student Ali Abbas Warz. The seminar discussion committee consisted of:
Prof. Dr. Maan Aboud Ali (Chairman)).
Assist.prof. Ahmed Jassim Mohammed (Member))
Dr. Ali Khalid Abdullah (Member and Supervisor))
During the episode, the researcher presented the study problem, which revolves around analyzing the impact of external shocks on the Iraqi financial market, given the Iraqi economy’s dependence on oil revenues and its vulnerability to global economic and monetary changes, and the need to estimate the dynamic effects of these shocks using a self-regressive Bayesian structural vector model.(SBVAR), highlighting the importance of the topic in understanding the fluctuations of the Iraqi stock market, supporting investment decisions, and promoting market stability.
The study plan included external shocks as the independent variables, namely oil price shocks, exchange rate shocks, global interest rate shocks, and the COVID-19 pandemic, and fluctuations in the Iraqi financial market as the dependent variable. The proposal adopted a quantitative analytical approach using a modelSBVAR is used to analyze the dynamic relationships between variables, and to estimate the strength of the impact of shocks and the duration of their effects on the market during the research period.
At the end of the session, the discussants presented a set of scientific and methodological observations aimed at developing the study plan, emphasizing the importance of defining market volatility metrics, refining the definition of external shocks, and clarifying the research gap, all of which contribute to raising the quality of the study and highlighting its importance in the Iraqi context..
This seminar is part of a series of scientific activities organized by the college to enhance the quality of scientific research for graduate students..